💫 Balance of Orbits and Niches
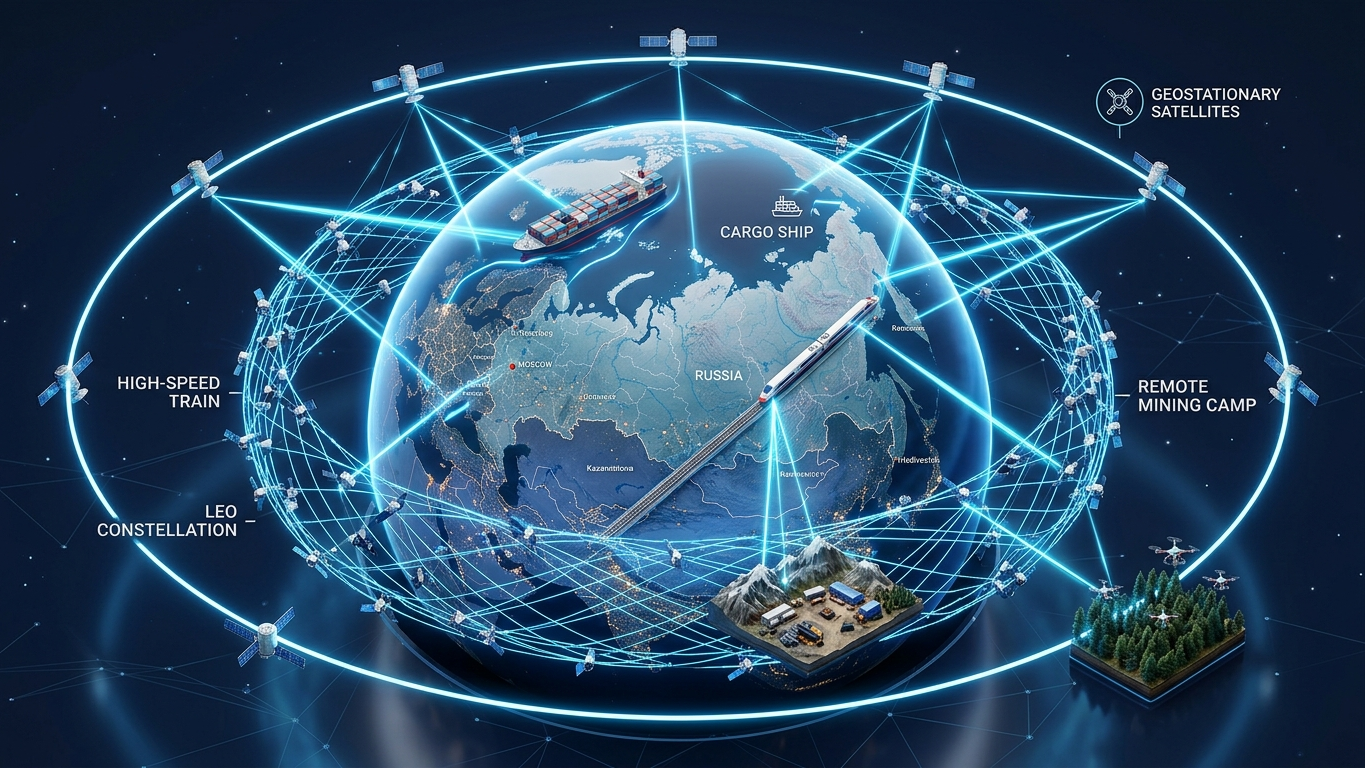
By 2030, the total demand of Russian users for satellite communications capacity will reach 95 GHz, compared to a planned constellation capacity of 112 GHz. The bulk of this capacity will be concentrated in Low Earth Orbit (LEO).
Key market balance indicators and the division of spheres of influence among operators were outlined by Alexey Volin, Director General of RSCC (Russian Satellite Communications Company) and Chairman of the “Satellite Communications” Industrial Competence Center, at the international conference SatComRus 2026.
Demand Architecture and Market Segmentation
While the expansion of fiber-optic networks provides telecom services to over 90% of Russia’s population, it covers only 20% of the country’s landmass. Geological exploration, extraction, and transportation of mineral resources in undeveloped areas will require approximately 9 GHz to serve 2 million shift workers. An additional 7 GHz is needed to bridge the digital divide in small settlements, and 4.5 GHz is required to equip the maritime and fishing fleets with internet access (increasing the number of connected vessels to 3,000).
SatComRus 2026 effectively finalized the division of niches among key industry players:
- RSCC and Gazprom Space Systems: Will retain traditional satellite TV (8–10 GHz), international operations (\~5 GHz), maritime vessels in international waters, and infrastructure redundancy.
- The free-standing Express-RV constellation: Will ensure high-quality connectivity in the high-latitude Arctic (north of 80° N).
- Bureau 1440 (LEO system): Will capture the mass broadband market, long-distance trains (11 GHz), civil UAVs (52 GHz), as well as autonomous and connected vehicles (4.5 GHz). Company representatives clarified that 24/7 commercial services for the Rassvet constellation are scheduled to launch by late 2027.
According to RSCC estimates, existing and planned capacity will suffice to meet national demand through 2030; however, the industry could face a new capacity deficit as early as 2035.
Technological Trends and State Connectivity
Yury Urlichich, Advisor to the Director General of RSCC, identified the main developmental vectors for the domestic space industry: transitioning to flat-panel satellite architectures, increasing power flux density on Earth, enhancing fault tolerance, and establishing multi-orbit systems with seamless handovers between spacecraft in different orbits.
A critical priority will be integrating LEO satellites with Air Traffic Management (ATM) systems. Projections indicate that up to 100,000 unmanned aerial vehicles (UAVs) will operate simultaneously in Russian airspace by 2030, necessitating a dedicated state-owned satellite monitoring infrastructure.
Import Substitution and Hardware Solutions
Russian satellite systems and equipment manufacturers demonstrated tangible progress toward technological sovereignty:
- JSC Reshetnev: Has fully transitioned its manufacturing to domestic electronic components, replacing what was previously a 90% reliance on imported parts.
- JSC Satellite System Gonets: Is completing tests on a new compact two-way modem for IoT and personal communications, targeting a commercial market release by late 2026. The earlier mandated 100% transition of fishing vessels with a displacement of 500+ tons to Gonets terminals successfully verified the operational capability of domestic hardware.
- JSC TsNIIMash: Will initiate development work in 2027 on payloads for geostationary spacecraft with throughput of up to 100 Gbps.
As participants concluded at SatComRus 2026, the market is evolving toward hybridization and technology partnerships, combining the hardware reliability of geostationary satellites with the flexibility and speed of LEO systems.
Source: SatComRus